

How to Sell a Tech Business: 4 Obstacles Owners Must Beat in 2026
By Ryan Kuhn. Since Ryan founded M&A advisor Kuhn Capital, the firm’s principals have initiated 80 mid-market tech industry M&A transactions worth more than $3 billion.
Selling a tech company in the $10M – 100M “mid-market” range is a career-defining milestone.
Yet many owners face buyers only once, and those buyers are pros: they negotiate deals for a living. This imbalance in experience and authority can devalue or even crater your deal.
Drawing on 30 years of M&A advisory experience and current industry data, I explain below how you can level the playing field and avoid the four most common pitfalls on the road to a successful exit.
In sum, they are:
- Unrealistic value expectations
- A shallow buyer pool
- Underprepared due diligence, and
- Insufficient confidentiality
The good news is that you can disarm these four traps with the right prep and advisory support.

But First, a Look at Tech M&A Today
Tech M&A remains strong heading into the second half of 2026:
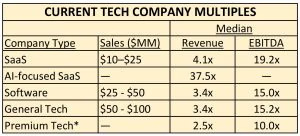
- SaaS deals: median multiple of 4.1x revenue
- Software deals: EBITDA multiples typically 11x–15x, depending on size and quality
- Private equity dry powder: over $2.6 trillion, fueling continued deal activity
- Hottest targets: AI-enabled, SaaS, and IP-rich companies
The Prospects for “Premium” Tech* Businesses Are Even Stronger. Buyers pay up for companies with:
- Strong recurring revenue (e.g., SaaS models)
- High growth — often 20%+ CAGR
- Above-average EBITDA margins for their segment
- A diversified, loyal customer base
- Proprietary, “blocking” IP (patented tech, unique software)
- Low client concentration
- A scalable model (e.g., cloud-based platforms)
- Strong management and operational controls
As noted in one of our M&A Factoids, “Year after year, the tech industry has reliably driven more M&A deal closings at the highest value per deal of any US mid-market industry.”
Four Deal Obstacles and Their Solutions
1) Setting an Unrealistic Value
Why it happens:
- Owners anchor on headline-grabbing mega-deal multiples that don’t apply to mid-market size
- They’re unaware of hidden value drivers — recurring revenue mix, client concentration, IP defensibility, and management’s grasp of emerging tech all swing multiples sharply
The fix: Hire an experienced M&A valuator — not a tax or estate-planning specialist. Someone whose analysis reflects real transaction dynamics, not tax-driven assumptions.
2) Failing to Create a Robust Auction Environment
Most DIY sale processes reach only about 10 buyers. That’s not enough. A real auction needs a critical mass of roughly 100 qualified strategic and financial buyers — vetted for financial capacity, deal track record, and a compelling reason to buy.
Why it matters: Competitive auctions with multiple bidders can drive valuations 30% higher than single- or dual-bidder sales — and meaningfully raise the odds of closing at all.
There are eight distinct types of equity investors, each suited to different targets and situations. Learn which one fits your company: See Your Best Acquirer.
3) Underestimating the Demands of Tech M&A Due Diligence
Tech due diligence (DD) requests often exceed 200 separate data items, including IP audits, code quality, data privacy, cybersecurity assessments, and AI compliance reviews. Gaps here don’t just slow things down, they discount value.
- Poor-quality information → higher perceived buyer risk → lower deal value
- Repeated delays kill momentum and raise suspicion of a cover-up
- Sellers who skip a proper virtual data room (VDR) spend 40% more executive time stuck in DD
The fix: Use a robust VDR and get M&A advisor help managing the sell-side process. Management must focus on running the business to avoid another deal killer: weak operating performance on the way to closing.T
4) Lax Confidentiality Controls
Tech deals carry outsized risk of leaks and talent flight. Tech executives are in high demand and easy to poach. Tech clients get nervous about supplier disruption at the first hint of a sale rumor.
The fix: Work with a deal advisor who can market your business anonymously at first, put safeguards against unauthorized disclosure in place, and help you devise ways to retain key employees through the transition.
Additional Best Practices
- Start prep 18 months before going to market. Give yourself time to find and fix value-killing issues. See: Quick Ways to Boost Value Before Sale and Bigger Projects That Increase Value More.
- Due diligence goes both ways. Vet finalist buyers too. Check their reputation with prior acquisition targets.
- Set ground rules early. Carefully review with your advisor the buyer’s Letter of Intent (LOI) before signing it. Negotiate transaction value and structure, set calendar expectations, protect source code, trade secrets, and confidential data, all before signing the document. Once signed, the buyer controls the process.
- Limit direct contact to one or two people per side and ban employee poaching in the NDA/LOI. Details here: The Perfect LOI.
Bottom Line: Tech M&A Still Favors the Prepared
Tech deals account for 28% of all mid-market M&A transactions and command the highest average valuations of any sector. But buyers are more selective than ever, widening the gap between “premium” businesses (see above) and everyone else.
Owners who invest in:
- Early exit planning and preparation
- A tech-sector-specific valuation
- Broad, precisely targeted buyer outreach
- A multi-bidder auction
- Thorough, advance internal due diligence
…stack the odds firmly in their favor.

Next Steps
- Score a complimentary valuation: Contact us for one grounded in current M&A transactions and modern NPV analysis.
- Request our M&A readiness assessment: Reach out — a brief call typically surfaces at least three value-boosting projects you can complete within 90 days.

Got more questions about how to close your M&A deal? Drop us an email.
Revised 7/20/26. © Kuhn Capital 2026. All Rights Reserved
Share post on:


Posted by:

Ryan Kuhn


08/27/2026
Ryan Kuhn is the founder of Kuhn Capital (bio). This article is not the product of AI. AI is a product of this article.


